Why does a 5% Treasury yield matter beyond the bond market?
The U.S. 10-year Treasury yield breached 5% on Sept.
The benchmark yield briefly exceeded 5%, compared with the 4.4% rate used by the Congressional Budget Office in February for long-term financial projections.[1] The move reflects hotter August inflation, surging oil prices, expectations of a Fed increase and heavy government and corporate borrowing…
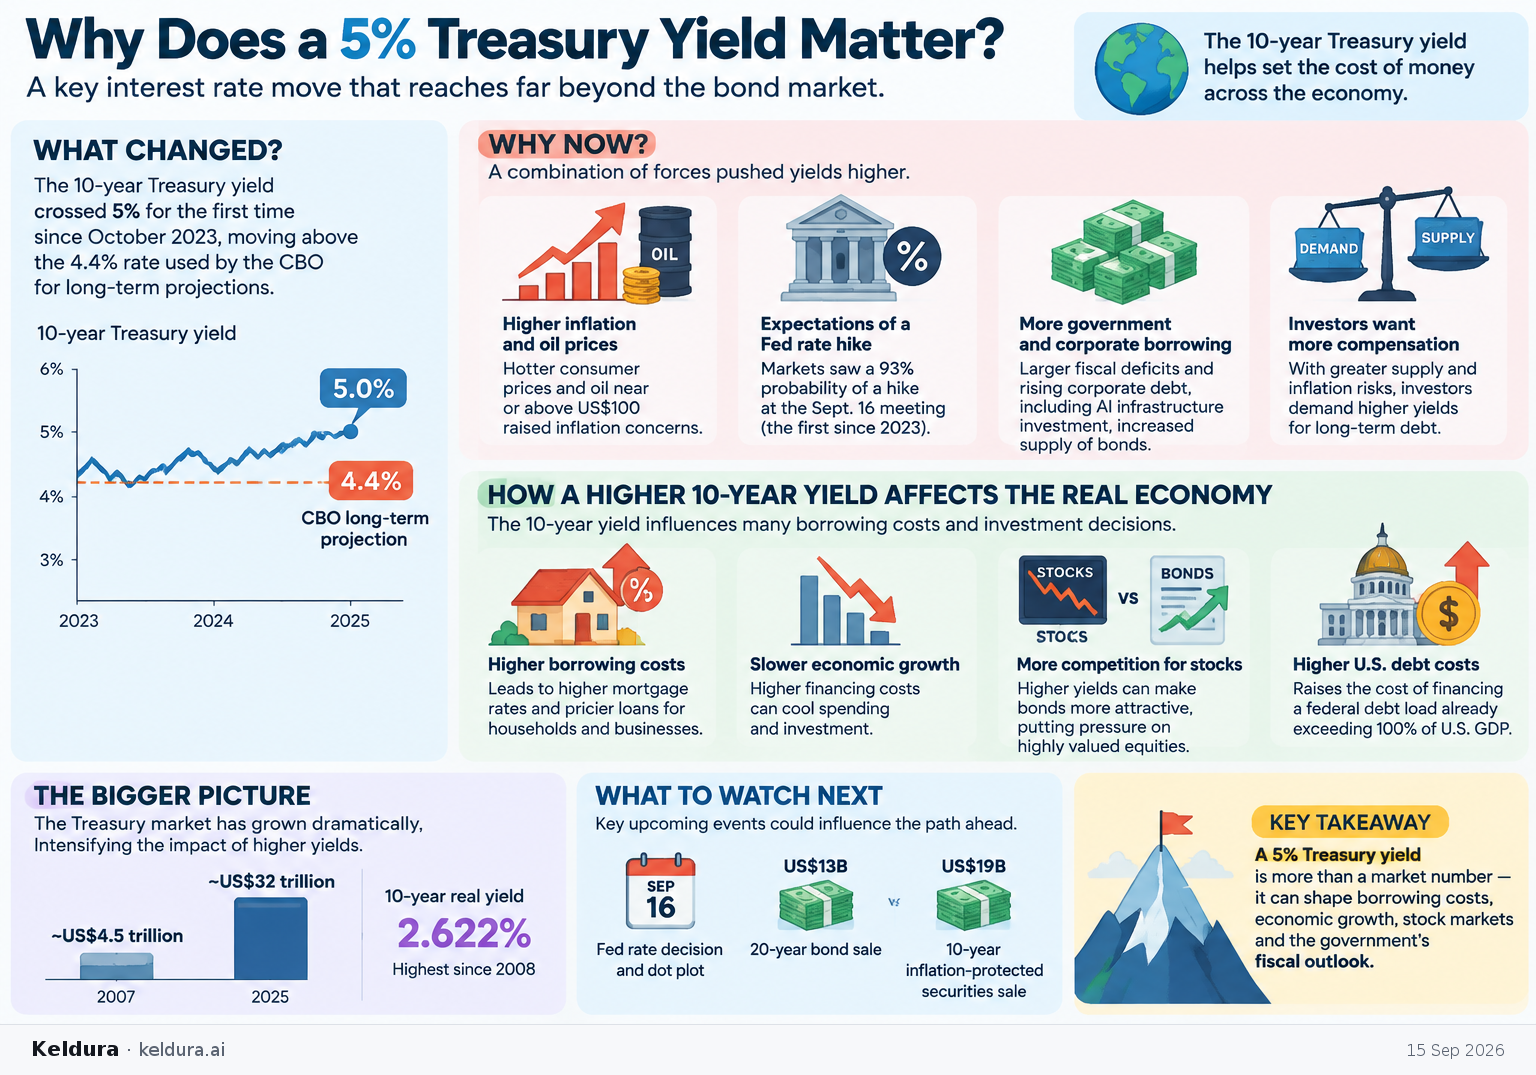
The benchmark yield briefly exceeded 5%, compared with the 4.4% rate used by the Congressional Budget Office in February for long-term financial projections.[1] The move reflects hotter August inflation, surging oil prices, expectations of a Fed increase and heavy government and corporate borrowing, rather than one isolated market shock.[2][3]
Why it matters: The 10-year yield influences mortgages and other borrowing costs, so a sustained increase can raise financing expenses for households and businesses, slow growth and make highly valued equities less attractive relative to bonds.[1][2][3] Higher yields also increase the cost of financing a federal debt load already exceeding 100% of U.S. GDP.[2]
Key insights: Oil is feeding directly into the rates debate: Brent approached US$110 a barrel, while escalating Middle East supply disruptions intensified concern that inflation will remain elevated.[2][3] | Markets assigned a 93% probability to a Fed hike at the conclusion of its Sept. 16 meeting, which would be the first increase since 2023.[3] | The sell-off has a structural component: investors are demanding more compensation for long-term debt as widening fiscal deficits and artificial-intelligence infrastructure investment create competing demands for capital.[2] | The Treasury market has expanded from about US$4.5 trillion in 2007 to roughly US$32 trillion, while the 10-year real yield reached 2.622%, its highest since 2008.[2][3]
Cheatsheet facts: What changed: The 10-year Treasury yield crossed 5% for the first time since October 2023, placing a key borrowing benchmark above the CBO’s 4.4% long-term projection assumption.[1][2] | Why now: Hotter consumer-price data, oil near or above US$100, expectations of Fed tightening and swelling public and corporate debt supply pushed yields higher.[2][3][7] | Watch next: Watch the Fed’s Sept. 16 rate decision and dot plot, plus demand at the Treasury’s US$13 billion 20-year bond sale and US$19 billion 10-year inflation-protected securities sale.[3]
The benchmark yield briefly exceeded 5%, compared with the 4.4% rate used by the Congressional Budget Office in February for long-term financial projections.[1] The move reflects hotter August inflation, surging oil prices, expectations of a Fed increase and heavy government and corporate borrowing, rather than one isolated market shock.[2][3]
Why it matters: The 10-year yield influences mortgages and other borrowing costs, so a sustained increase can raise financing expenses for households and businesses, slow growth and make highly valued equities less attractive relative to bonds.[1][2][3] Higher yields also increase the cost of financing a federal debt load already exceeding 100% of U.S. GDP.[2]
Key insights: Oil is feeding directly into the rates debate: Brent approached US$110 a barrel, while escalating Middle East supply disruptions intensified concern that inflation will remain elevated.[2][3] | Markets assigned a 93% probability to a Fed hike at the conclusion of its Sept. 16 meeting, which would be the first increase since 2023.[3] | The sell-off has a structural component: investors are demanding more compensation for long-term debt as widening fiscal deficits and artificial-intelligence infrastructure investment create competing demands for capital.[2] | The Treasury market has expanded from about US$4.5 trillion in 2007 to roughly US$32 trillion, while the 10-year real yield reached 2.622%, its highest since 2008.[2][3]
Cheatsheet facts: What changed: The 10-year Treasury yield crossed 5% for the first time since October 2023, placing a key borrowing benchmark above the CBO’s 4.4% long-term projection assumption.[1][2] | Why now: Hotter consumer-price data, oil near or above US$100, expectations of Fed tightening and swelling public and corporate debt supply pushed yields higher.[2][3][7] | Watch next: Watch the Fed’s Sept. 16 rate decision and dot plot, plus demand at the Treasury’s US$13 billion 20-year bond sale and US$19 billion 10-year inflation-protected securities sale.[3]
X copy pack
[1] Spike on 10-year bond yields renews concerns over U.S. debt - The Washington Post — washingtonpost.com[2] US 10-year Treasury yield breaches 5% as inflation, supply worries mount | The Straits Times — straitstimes.com[3] 10-year Treasury yield touches 5% as all eyes on Fed - Nikkei Asia — asia.nikkei.com[7] Fed's table is set for a rate hike, a first under Warsh | Reuters — reuters.comRead in BriefingsPost to X