EU ministers want investment to flow more freely across borders, but what must happen before stronger central supervision begins?
On October 9, 2026, EU finance ministers agreed in Luxembourg to expand the powers of the European Securities and Markets Authority.
Why it matters: The reform links stronger central oversight to Europe's effort to build a unified capital market: policymakers want savings to move more readily into investments across national borders rather than r…
The EU wants a smaller trade imbalance, but can talks advance while China presses for access to restricted chipmaking equipment?
On October 9, 2026, China and EU trade envoys were wrapping up two days of negotiations in Beijing over growing trade imbalances.
Why it matters: The negotiations bring together two competing priorities: the EU wants to rebalance trade after China's surplus reached 360 billion euros last year, while China wants access to technology restricted…
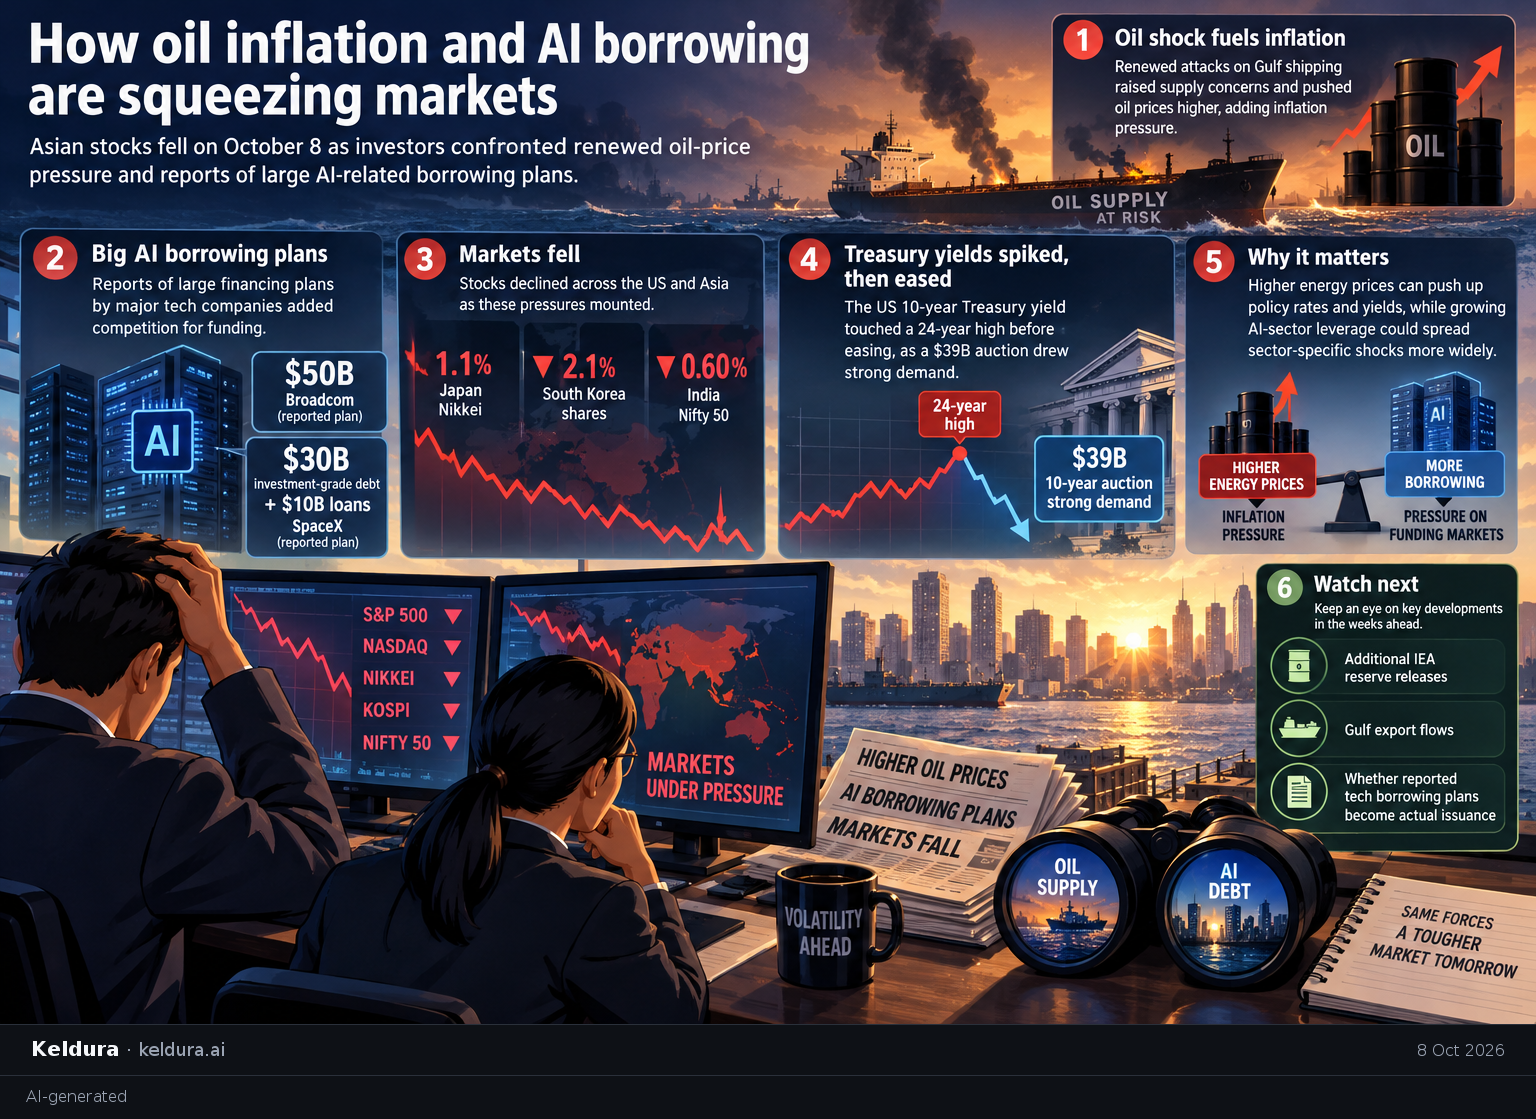
Asian stocks fell on October 8 as investors confronted renewed oil-price pressure and reports of large AI-related borrowing plans.
Why it matters: The squeeze has two channels: expensive energy raises inflation pressure, while corporate and government borrowers compete for funding. The IMF identifies higher energy prices as a force pushing up p…
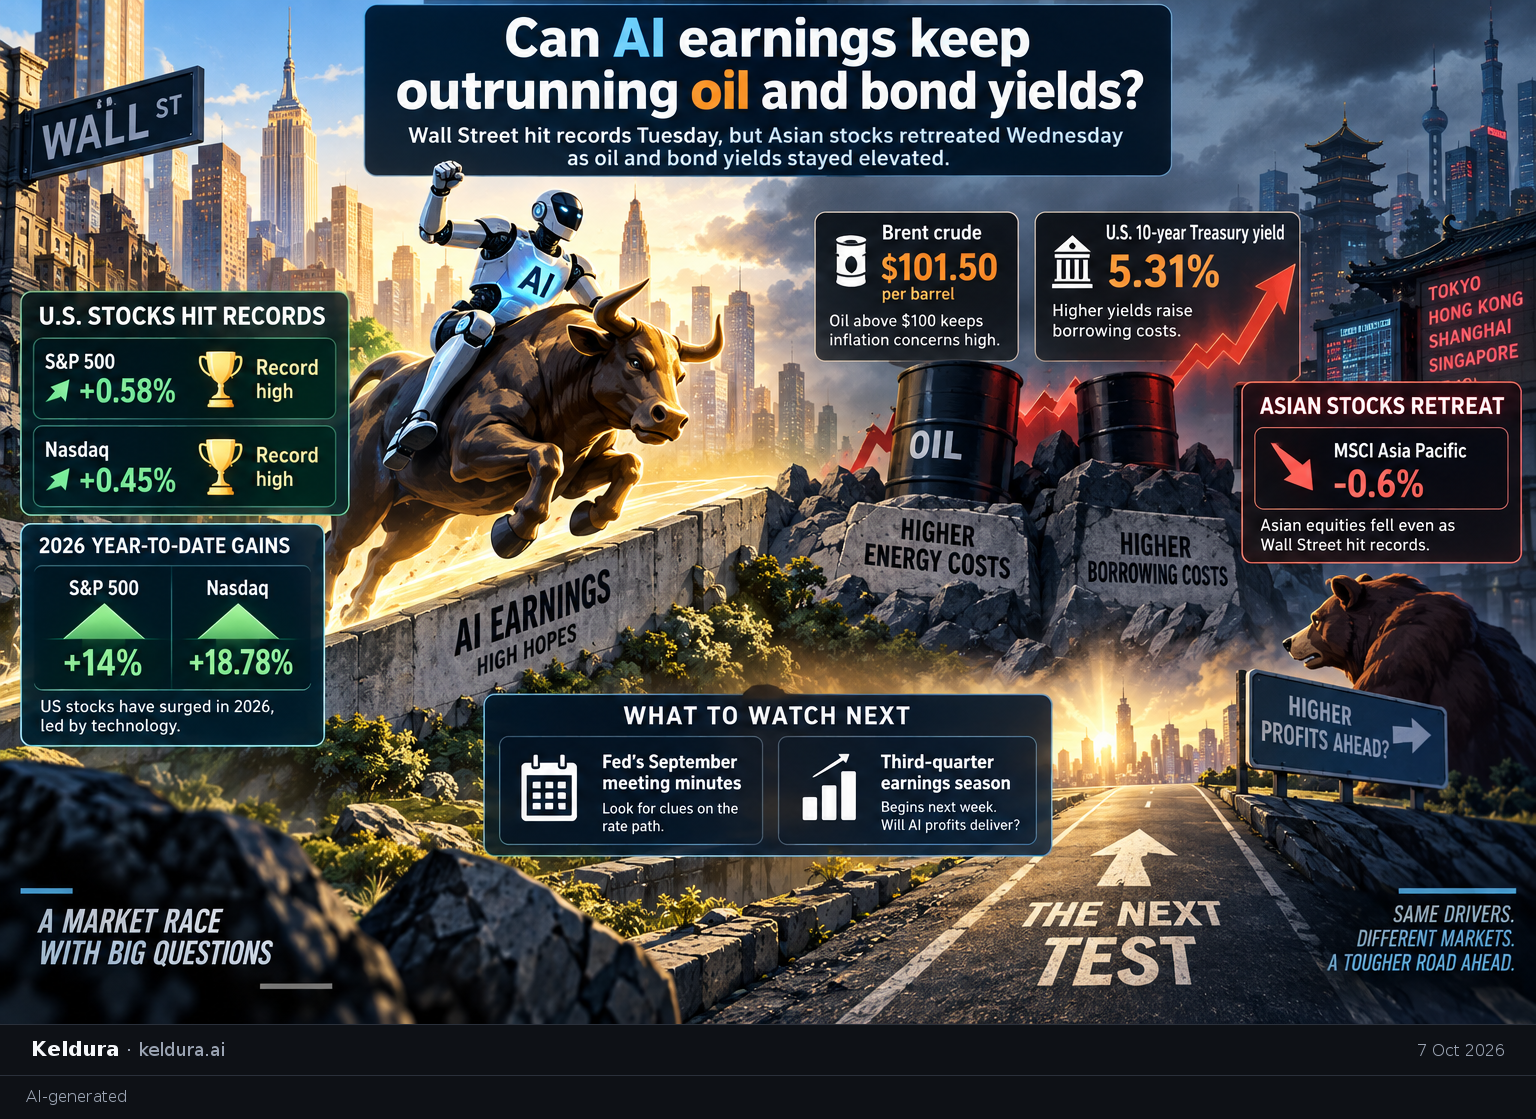
Wall Street hit records Tuesday, but Asian stocks retreated Wednesday as oil and bond yields stayed elevated.
Why it matters: US equity strength is increasingly tied to a concentrated group of cash-rich AI and mega-cap companies, making the approaching earnings season a test of whether massive AI investment is producing eno…
The S&P 500 and Nasdaq reached records, while Asian equities fell 0.6% and US equity futures reversed earlier gains.[1][2]
Why now
AI earnings optimism supported US stocks, but Brent above $100 and high government-bond yields continued to raise inflation and financing concerns.[1][3]
Watch next
Track the Fed’s September meeting minutes and the third-quarter earnings season beginning next week for evidence on rates and AI-related profits.[3][4]
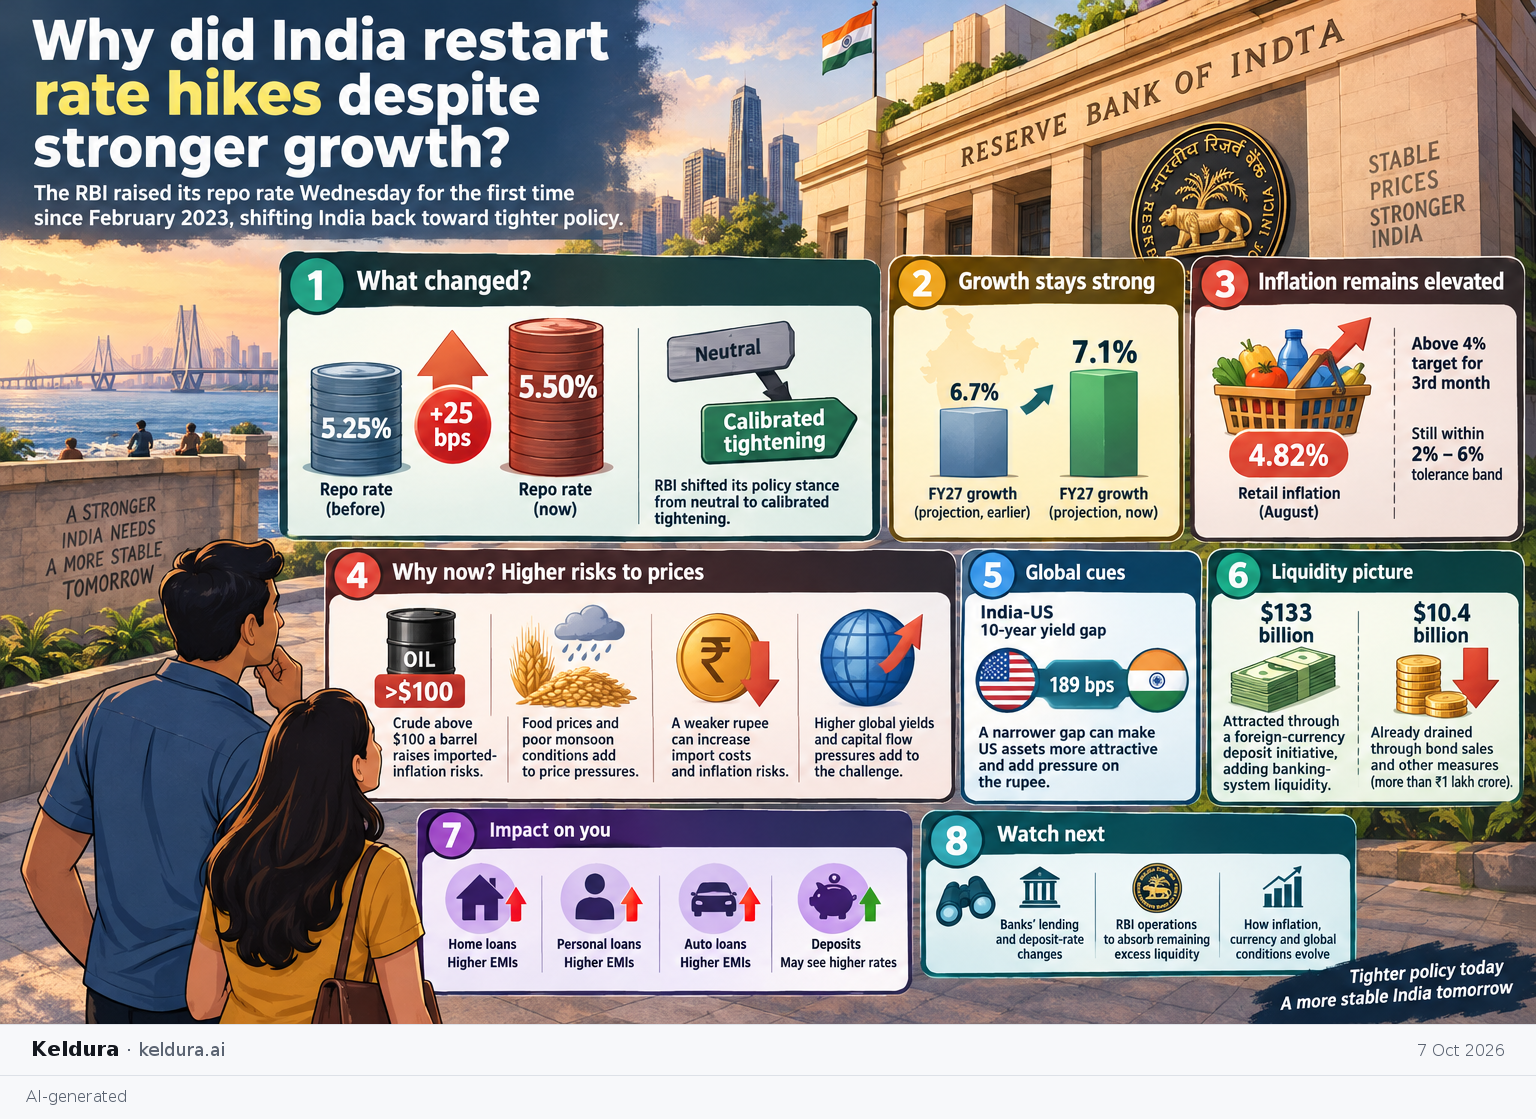
The RBI raised its repo rate Wednesday for the first time since February 2023, shifting India back toward tighter policy.
Why it matters: The increase can raise payments on benchmark-linked home, personal and vehicle loans, while potentially supporting deposit rates. It also shows how an energy-importing economy can tighten policy even…
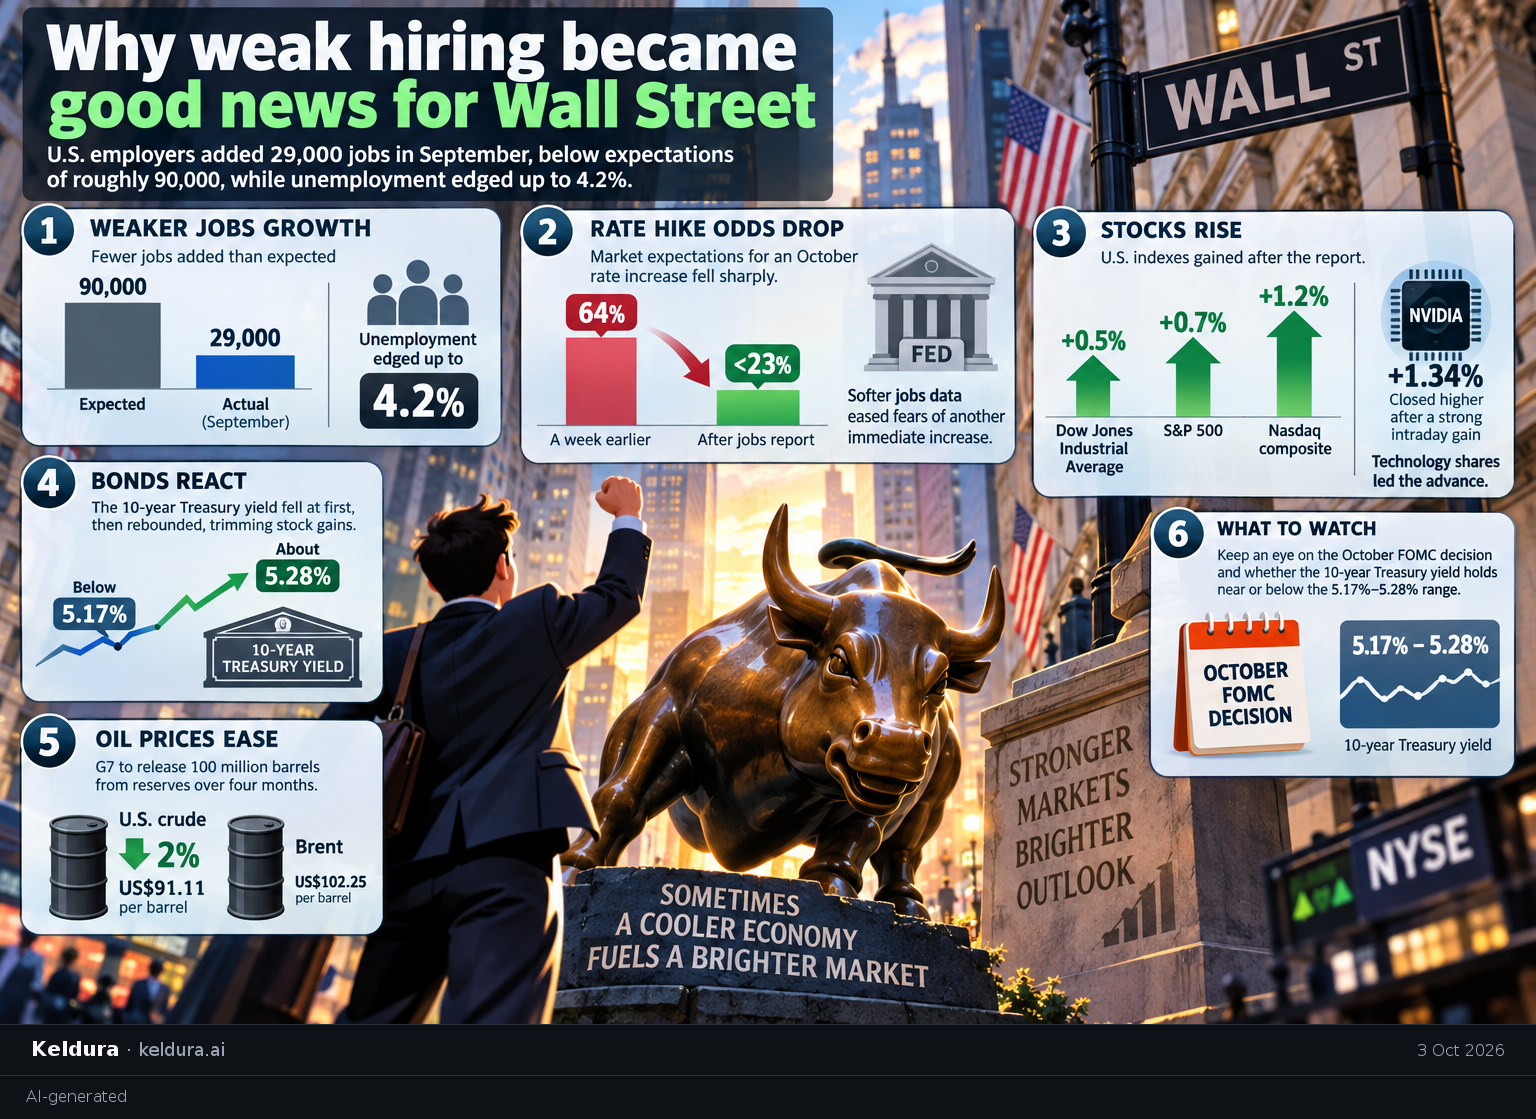
U.S. employers added 29,000 jobs in September, below expectations of roughly 90,000, while unemployment edged up to 4.2%.
Why it matters: Slower hiring eased fears that an overheated economy would intensify inflation and force the Federal Reserve to tighten policy again, supporting both bonds and rate-sensitive stocks. But oil and dies…
Payroll growth slowed to 29,000 and unemployment reached 4.2%, sharply reducing market expectations for an October Fed rate increase.[2][3]
Why now
The Federal Reserve recently raised its main rate for the first time in three years, so softer employment data eased concern that persistent inflation would require another immediate increase.[1]
Watch next
Watch the October FOMC decision and whether the 10-year Treasury yield holds near or below the 5.17%-5.28% range traversed after the jobs report.[1][3][4]
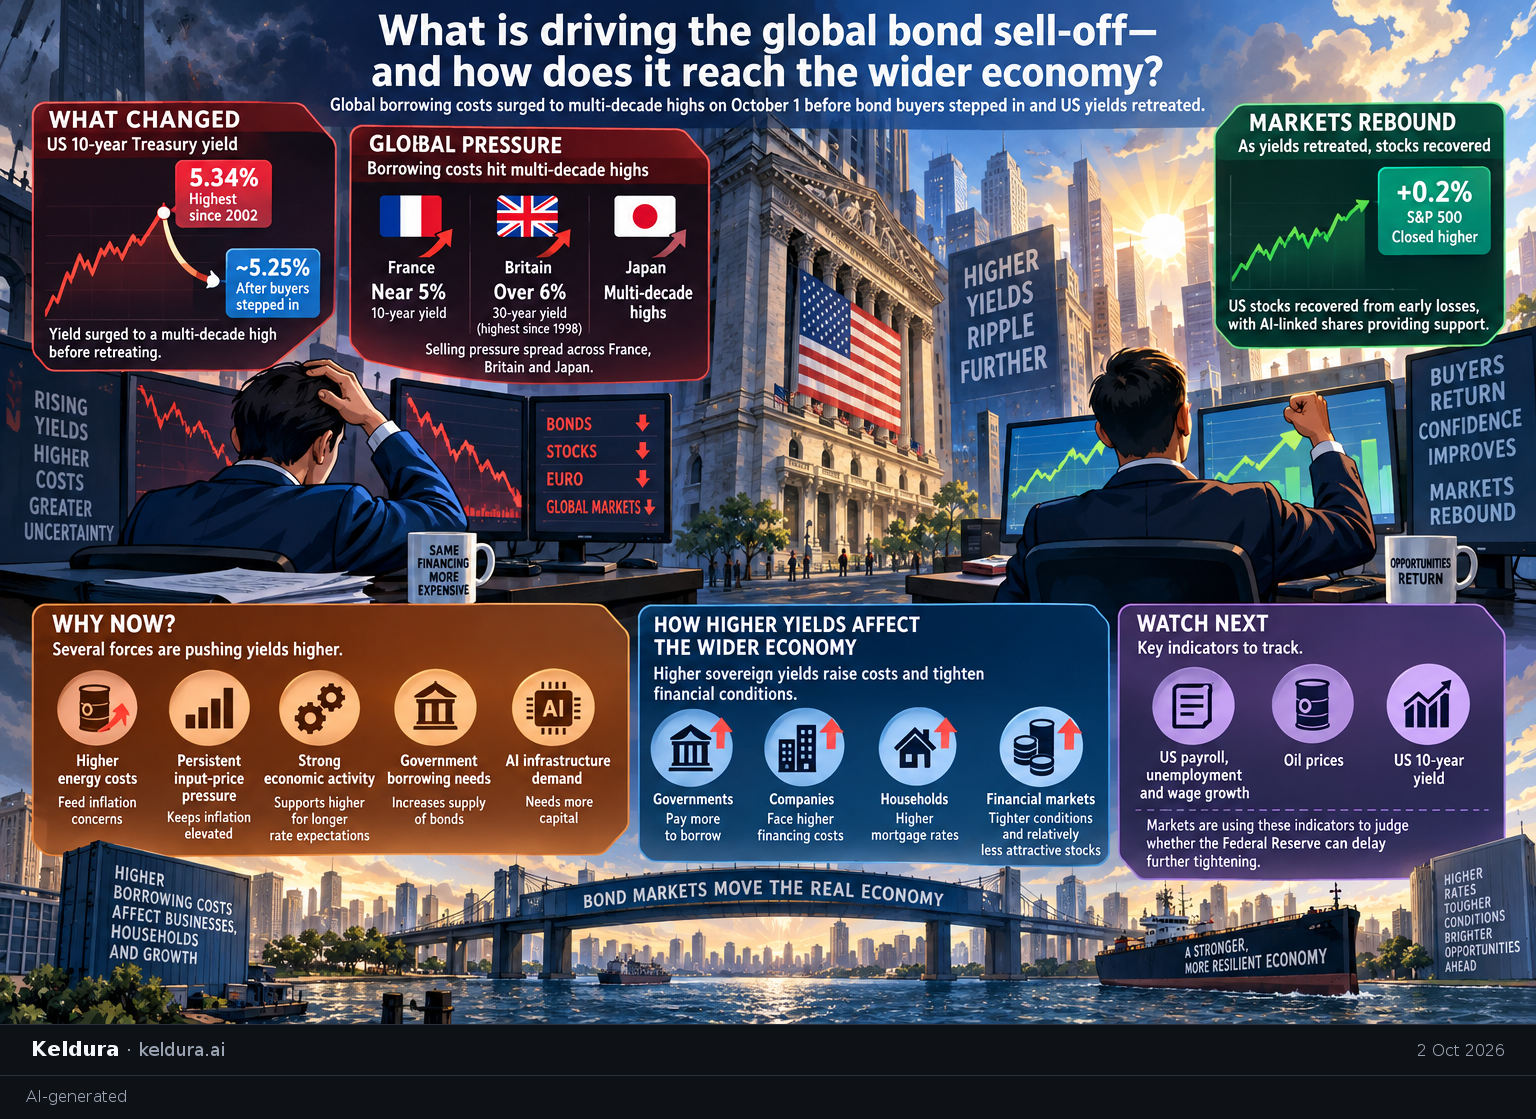
Global borrowing costs surged to multi-decade highs on October 1 before bond buyers stepped in and US yields retreated.
Why it matters: Higher sovereign yields raise financing costs for governments, companies and mortgage borrowers, tighten financial conditions and reduce the relative appeal of stocks; advanced economies already paid…
The US 10-year yield touched 5.34%, its highest since 2002, before retreating toward 5.25%; comparable selling pushed borrowing costs in France, Britain and Japan to multi-decade highs.[1][3][4]
Why now
Higher energy costs, persistent input-price pressure, strong economic activity, government borrowing needs and capital demand from AI infrastructure are collectively increasing inflation and interest-rate expectations.[1][4][5][6]
Watch next
Track the published US payroll, unemployment and wage-growth figures, alongside oil prices and the US 10-year yield; markets are using those observable indicators to judge whether the Federal Reserve can delay further tightening.[2][3]
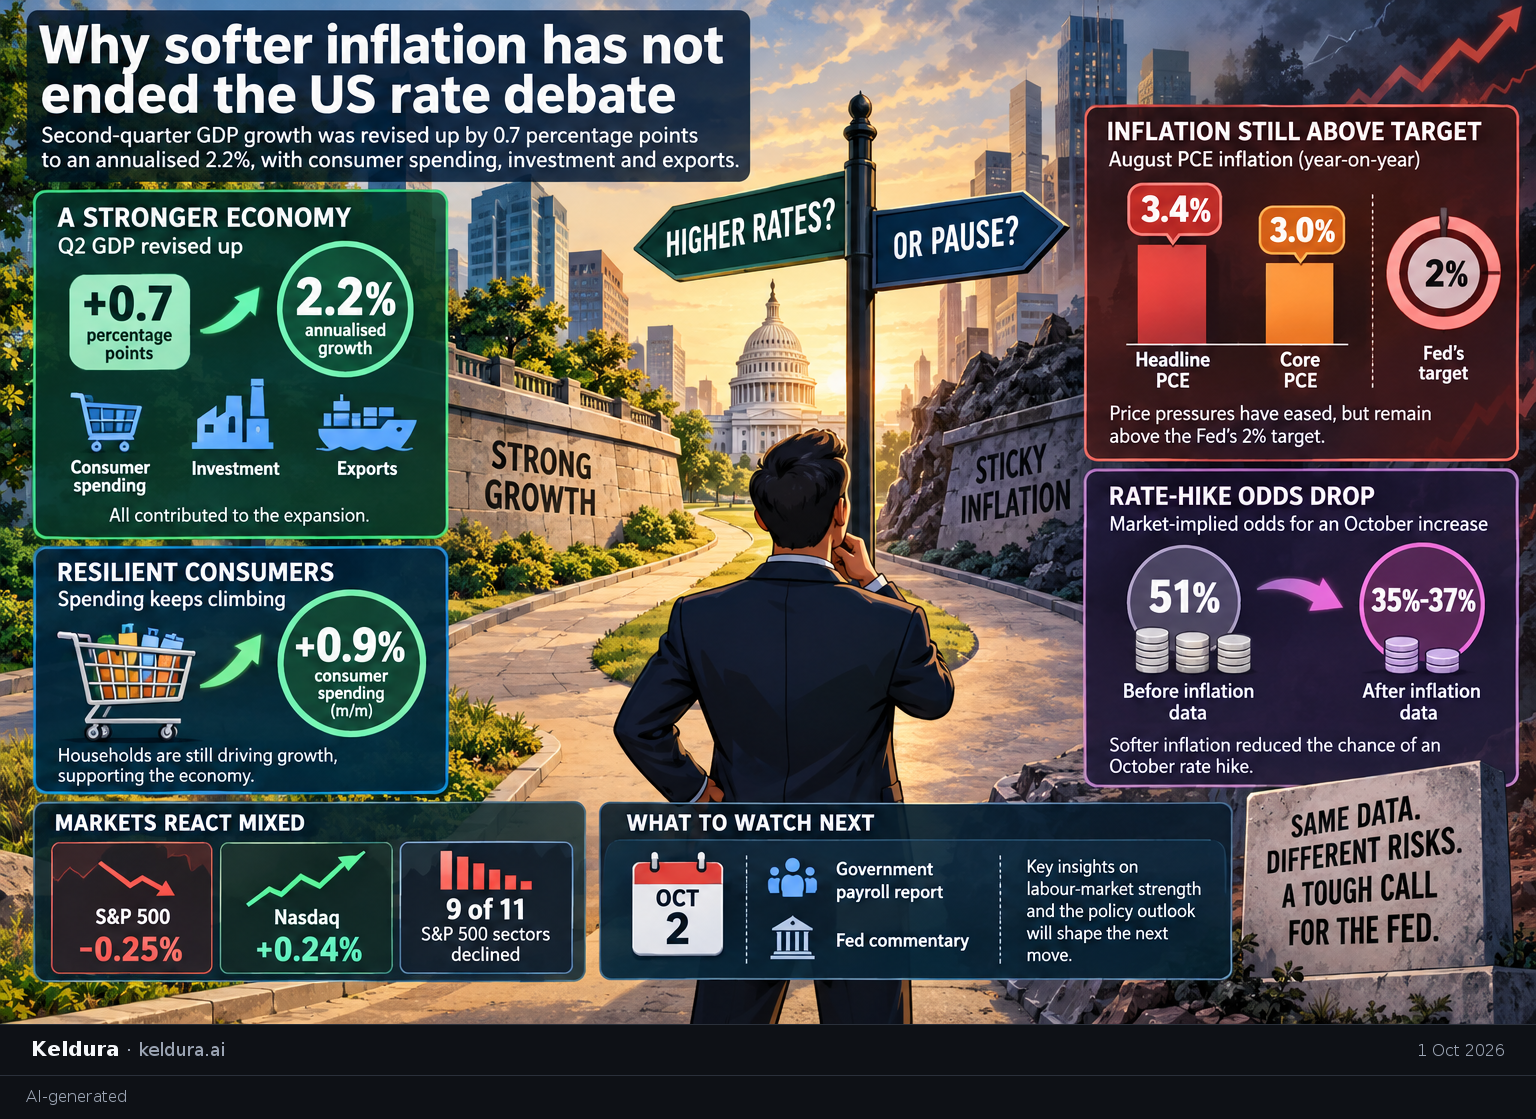
Second-quarter GDP growth was revised up by 0.7 percentage points to an annualised 2.2%, with consumer spending, investment and exports.
Why it matters: The combination leaves the Fed facing a two-sided problem: inflation remains above its 2% target, but softer monthly price growth reduces the urgency to raise rates immediately. Strong spending and A…
Q2 GDP was revised to 2.2%, August PCE inflation came in at 3.4% year-on-year, and October rate-hike odds dropped to about 35%-37% [3][4][9].
Why now
Inflation rose less than expected while consumer spending surged 0.9%, producing a mix of softer price momentum and resilient demand [9].
Watch next
The Oct. 2 government payroll report and subsequent Fed commentary will provide observable evidence on labour-market strength and policymakers’ assessment of inflation [2][4].
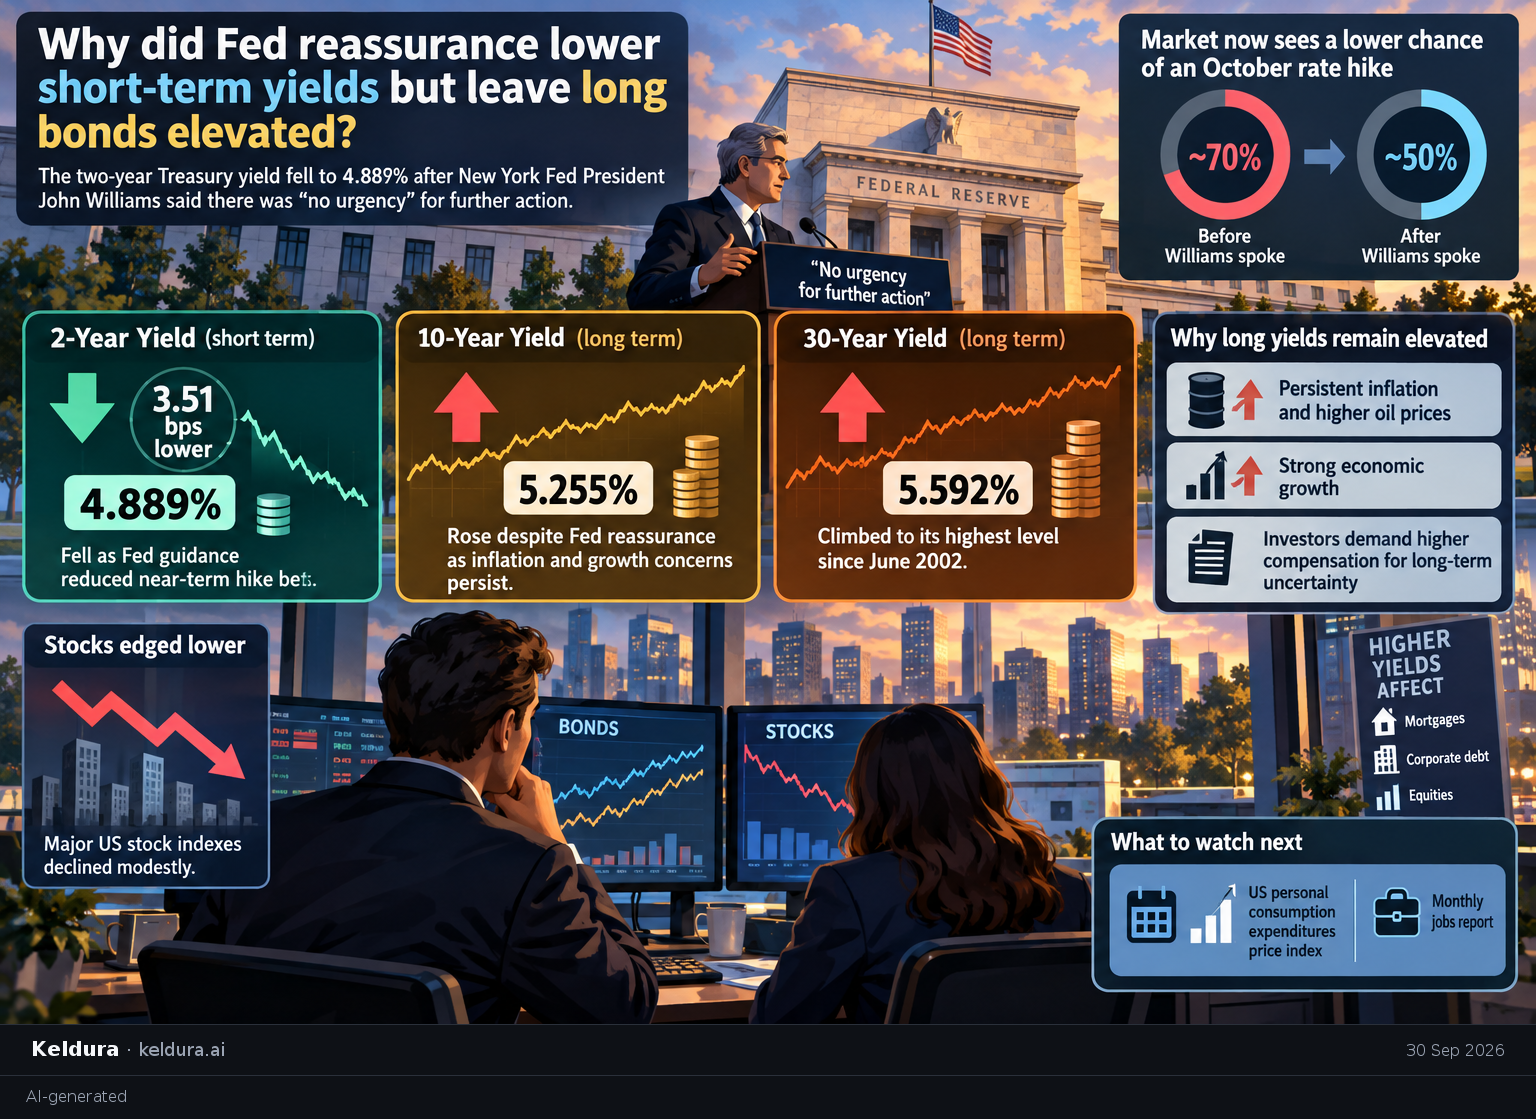
The two-year Treasury yield fell to 4.889% after New York Fed President John Williams said there was “no urgency” for further action.
Why it matters: The divergence reflects two different bets: short maturities track the next Fed decision, while longer maturities also absorb persistent inflation, energy costs and the prospect that strong growth wi…
The two-year yield fell 3.51 basis points to 4.889%, while the 10-year rose to 5.255% and the 30-year climbed to 5.592%.[1]
Why now
Williams signalled no urgency after September’s rate increase, but investors still faced elevated inflation concerns, higher oil prices and strong economic growth.[1][7]
Watch next
The next observable tests are the US personal consumption expenditures price index and the monthly jobs report due later in the week.[1]
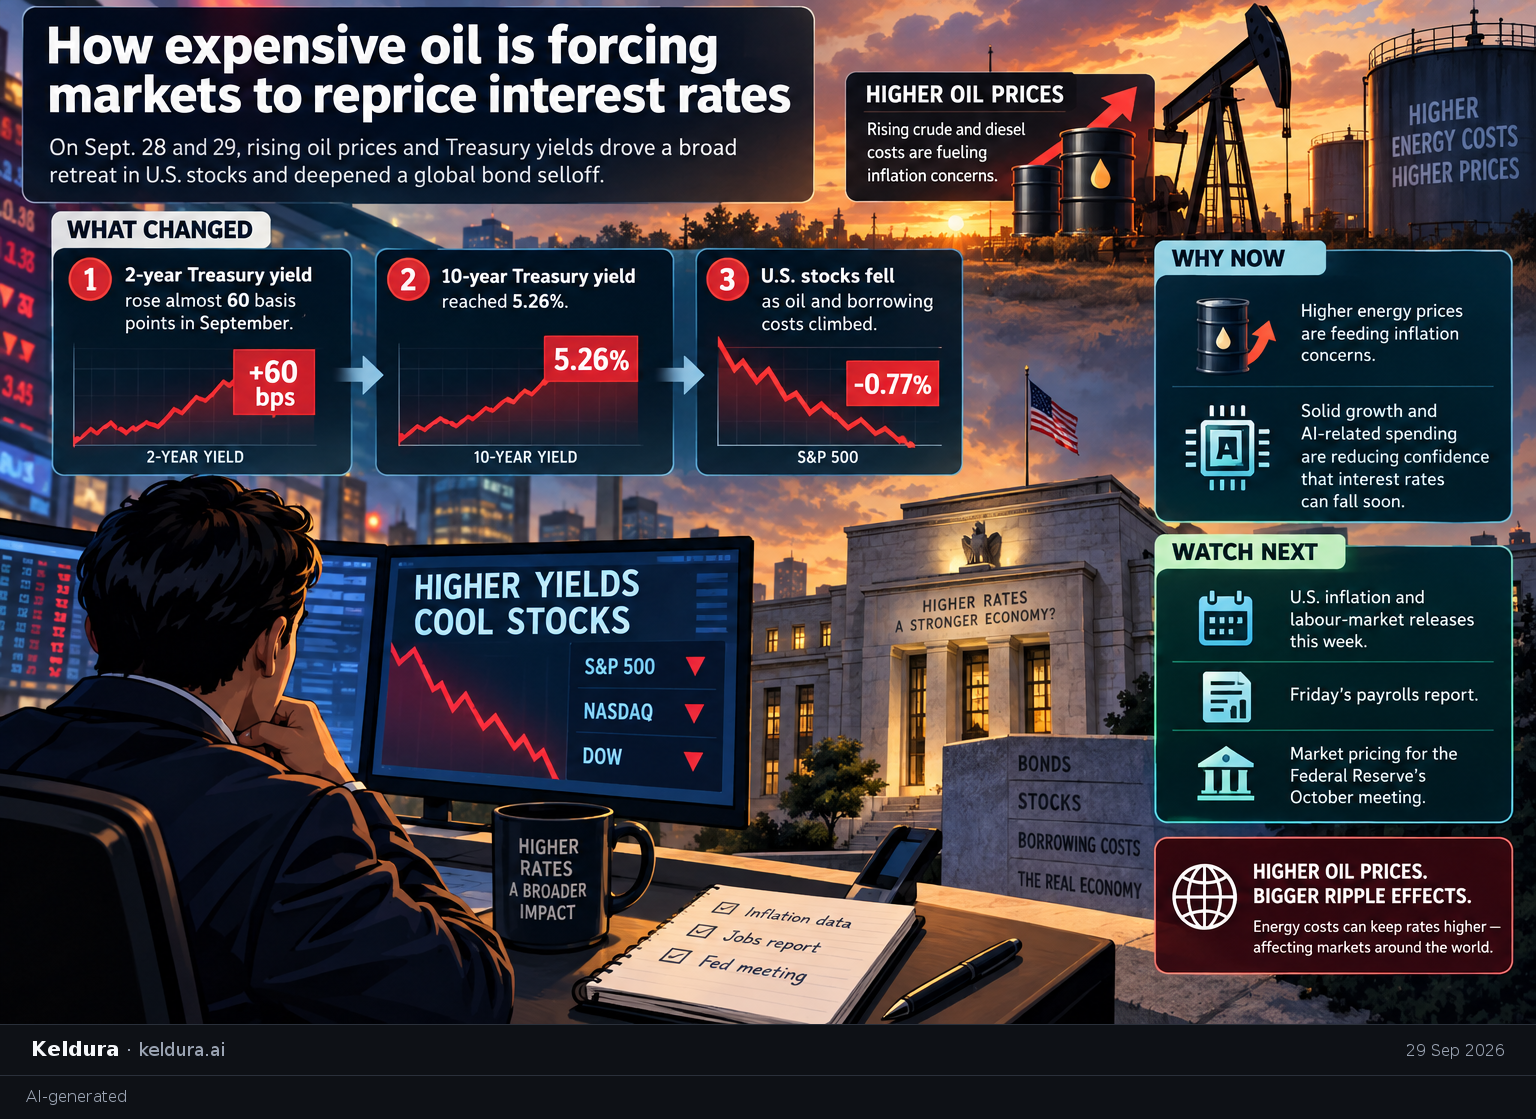
On Sept. 28 and 29, rising oil prices and Treasury yields drove a broad retreat in U.S. stocks and deepened a global bond selloff.
Why it matters: The mechanism reaches beyond bond traders: oil-driven inflation can keep policy rates elevated, higher Treasury yields raise borrowing costs across the economy, and more attractive bond returns can r…
Two-year Treasury yields rose almost 60 basis points in September, the 10-year yield reached 5.26%, and U.S. stocks fell as oil and borrowing costs climbed.[1][4][7]
Why now
Higher energy prices are feeding inflation concerns while solid growth and AI-related spending are reducing confidence that interest rates can fall soon.[1][4]
Watch next
Track this week’s U.S. inflation and labour-market releases, Friday’s payrolls report, and market pricing for the Federal Reserve’s October meeting.[4]
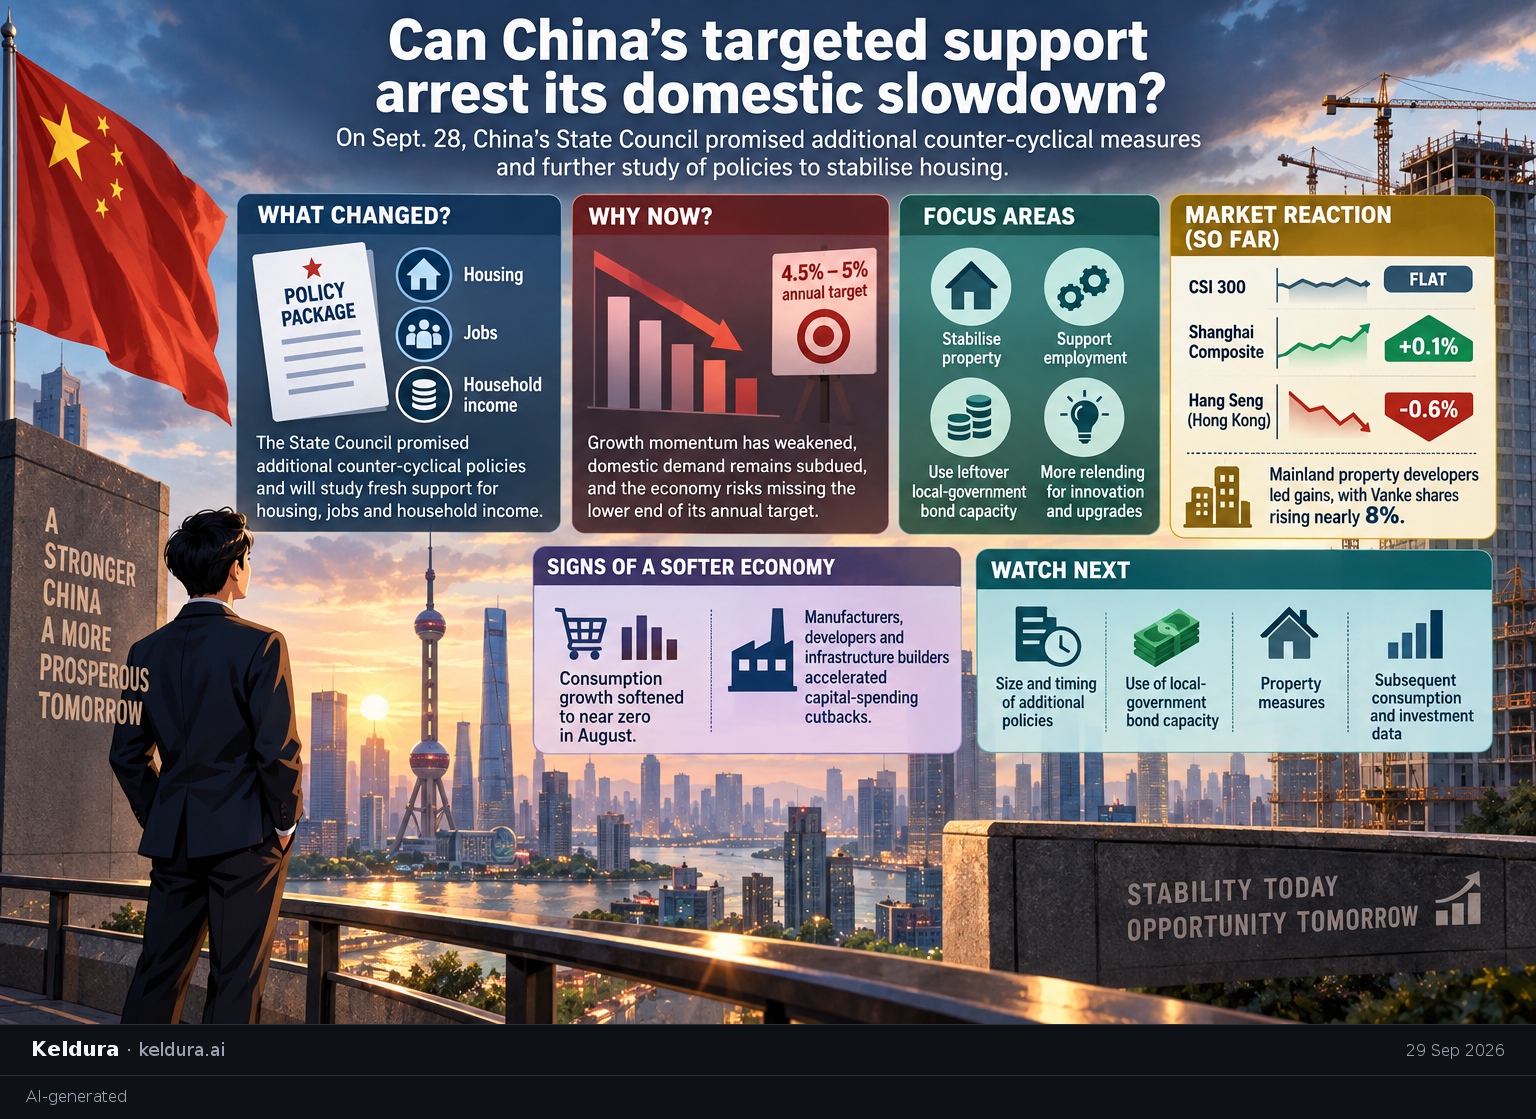
On Sept. 28, China’s State Council promised additional counter-cyclical measures and further study of policies to stabilise housing.
Why it matters: Beijing is trying to support demand without relying on a large, broad stimulus package, reflecting concerns about local-government debt and diminishing returns from consumer subsidies; the effectiven…
The State Council promised additional counter-cyclical policies and said it would study fresh support for housing, jobs and household income.[3]
Why now
Growth momentum has weakened, domestic demand remains subdued, and the economy risks missing the lower end of its 4.5%-5% annual target.[3]
Watch next
Monitor the size and timing of additional policies, use of leftover local-government bond capacity, property measures and subsequent consumption and investment data.[3]
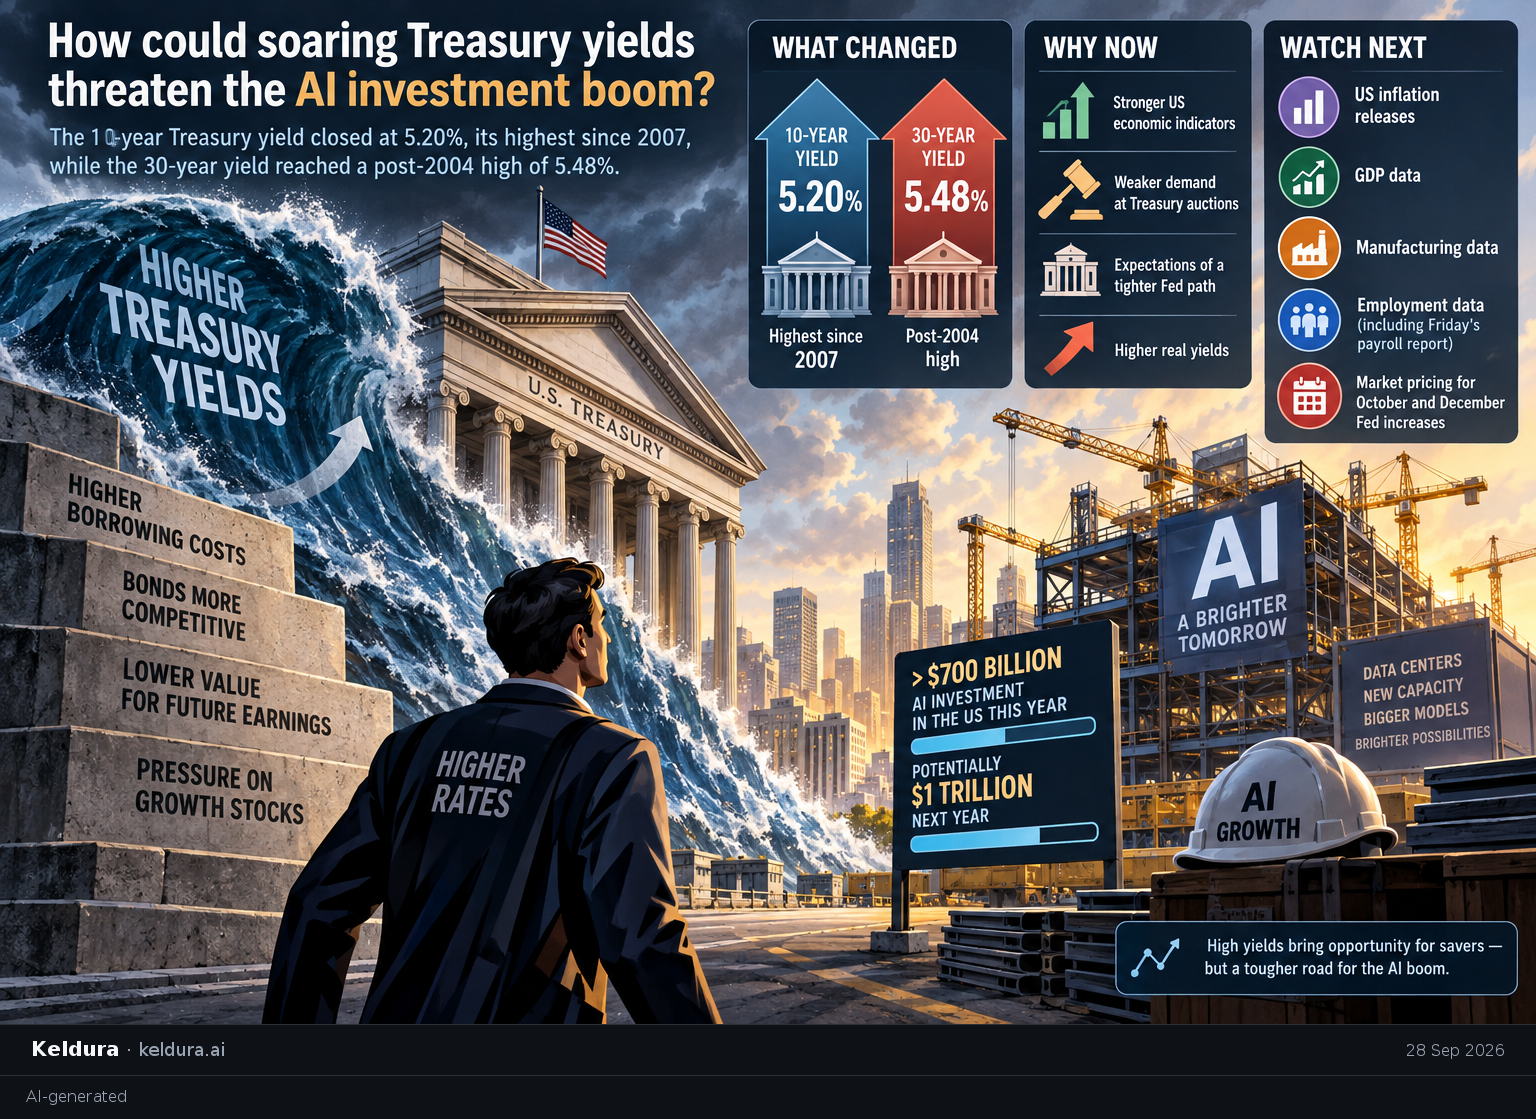
The 10-year Treasury yield closed at 5.20%, its highest since 2007, while the 30-year yield reached a post-2004 high of 5.48%.
Why it matters: Higher risk-free yields make bonds more competitive with equities, increase corporate borrowing costs and reduce the present value of distant earnings—an especially important combination for AI-relat…
The 10-year Treasury yield reached 5.20%, its highest since 2007, and the 30-year yield reached a post-2004 high of 5.48%.[5]
Why now
Strong US indicators, weak demand at Treasury auctions and expectations of a tighter Fed path pushed real yields higher.[5]
Watch next
Monitor the upcoming US inflation, GDP, manufacturing and employment releases, including Friday’s payroll report, alongside market pricing for October and December Fed increases.[1][5]
That's the desk. Every cheatsheet here started as a link. Yours can too.