Why long-term borrowing costs are rising beyond the Fed’s control
The 30-year Treasury yield reached 5.48% and the 10-year yield hit 5.20% as investors responded to high energy costs, resilient growth.
The 30-year Treasury yield reached 5.48% and the 10-year yield hit 5.20% as investors responded to high energy costs, resilient growth, government spending and persistent inflation. [5] Longer-term rates also reflect heavy borrowing for federal deficits and technology companies’ data-center constru…
The 30-year Treasury yield reached 5.48% and the 10-year yield hit 5.20% as investors responded to high energy costs, resilient growth, government spending and persistent inflation. [5] Longer-term rates also reflect heavy borrowing for federal deficits and technology companies’ data-center construction, so they do not move solely with the Federal Reserve’s policy rate. [6] Mortgage rates have consequently climbed to about 7%, around their highest level in two years. [5]
Why it matters: Higher government-bond yields flow into household and corporate financing while making bonds more competitive with equities. [5][7] That creates a market tension in which strong growth and corporate profits can support stocks even as the associated inflation and borrowing pressures lift discount rates and financing costs. [5]
Key insights: The selloff is global: Germany’s 10-year Bund yield briefly exceeded 3.6%, its highest in 17 years, while Japan’s 10-year yield reached its highest since 1996. [5] | The Federal Reserve raised its policy rate by a quarter percentage point on September 16, and futures indicated a greater than 60% probability of another increase at its October meeting. [7] | September payrolls are expected to rise by 100,000 while unemployment remains at 4.2%, according to a Reuters poll. [7] | US consumer sentiment fell 7% from August to 48.1 in September, its second-lowest reading since the survey began in 1952, as high gasoline prices weighed on households. [4]
Cheatsheet facts: What changed: The US 30-year yield rose to 5.48%, the 10-year yield reached 5.20% and 30-year mortgage rates climbed to about 7%. [5] | Why now: Investors are demanding more compensation amid expensive energy, persistent inflation, resilient growth and heavy public and technology-sector borrowing. [5][6] | Watch next: Watch the upcoming PCE inflation reading and the October 2 employment report for evidence affecting the Fed’s rate path. [7]
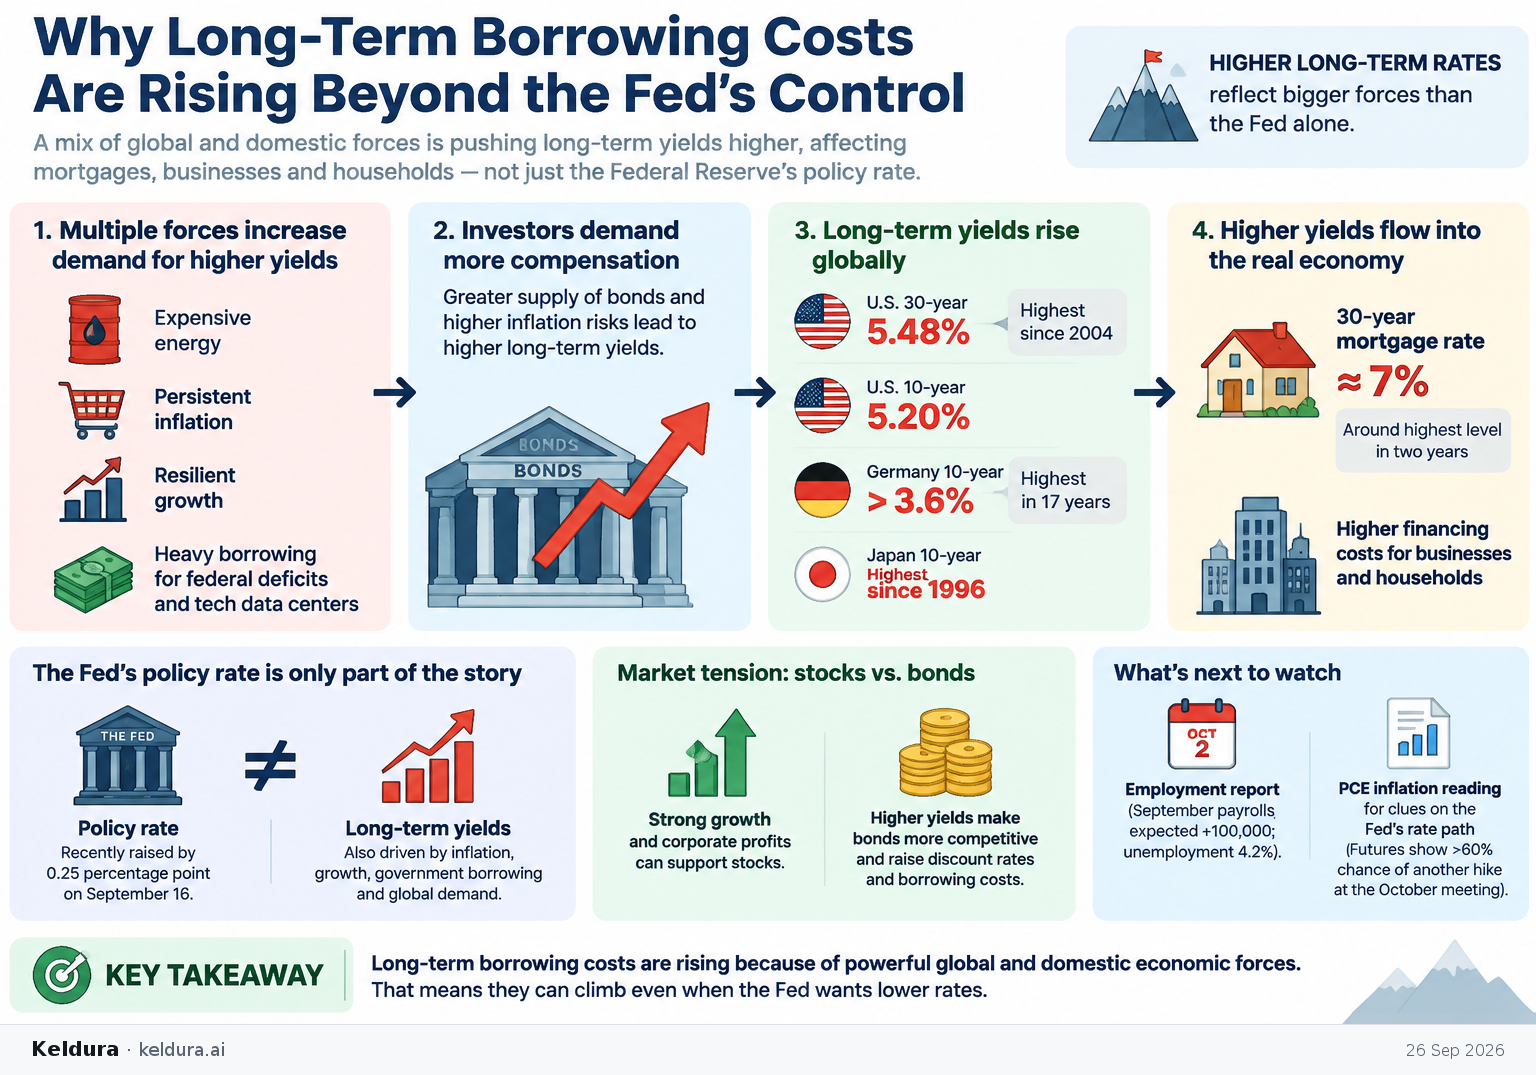
The 30-year Treasury yield reached 5.48% and the 10-year yield hit 5.20% as investors responded to high energy costs, resilient growth, government spending and persistent inflation. [5] Longer-term rates also reflect heavy borrowing for federal deficits and technology companies’ data-center construction, so they do not move solely with the Federal Reserve’s policy rate. [6] Mortgage rates have consequently climbed to about 7%, around their highest level in two years. [5]
Why it matters: Higher government-bond yields flow into household and corporate financing while making bonds more competitive with equities. [5][7] That creates a market tension in which strong growth and corporate profits can support stocks even as the associated inflation and borrowing pressures lift discount rates and financing costs. [5]
Key insights: The selloff is global: Germany’s 10-year Bund yield briefly exceeded 3.6%, its highest in 17 years, while Japan’s 10-year yield reached its highest since 1996. [5] | The Federal Reserve raised its policy rate by a quarter percentage point on September 16, and futures indicated a greater than 60% probability of another increase at its October meeting. [7] | September payrolls are expected to rise by 100,000 while unemployment remains at 4.2%, according to a Reuters poll. [7] | US consumer sentiment fell 7% from August to 48.1 in September, its second-lowest reading since the survey began in 1952, as high gasoline prices weighed on households. [4]
Cheatsheet facts: What changed: The US 30-year yield rose to 5.48%, the 10-year yield reached 5.20% and 30-year mortgage rates climbed to about 7%. [5] | Why now: Investors are demanding more compensation amid expensive energy, persistent inflation, resilient growth and heavy public and technology-sector borrowing. [5][6] | Watch next: Watch the upcoming PCE inflation reading and the October 2 employment report for evidence affecting the Fed’s rate path. [7]
X copy pack
[5] Global bond selloff rolls on, US 30-year yield at highest since 2004 | The Straits Times — straitstimes.com[6] Why mortgage rates are rising even as Trump demands lower interest rates - Los Angeles Times — latimes.com[7] Jobs report, inflation data to test US rate path, economic strength | 95.5 WIFC — wifc.com[4] Americans still feel worse about the economy than at almost any point in modern history | CNN Business — cnn.comRead in BriefingsPost to X