Why did Fed reassurance lower short-term yields but leave long bonds elevated?
The two-year Treasury yield fell to 4.889% after New York Fed President John Williams said there was “no urgency” for further action.
The two-year Treasury yield fell to 4.889% after New York Fed President John Williams said there was “no urgency” for further action, reducing the market-implied probability of an October quarter-point increase from nearly 70% to about 50%.[1] The 10-year yield nevertheless rose to 5.255%, the 30-y…
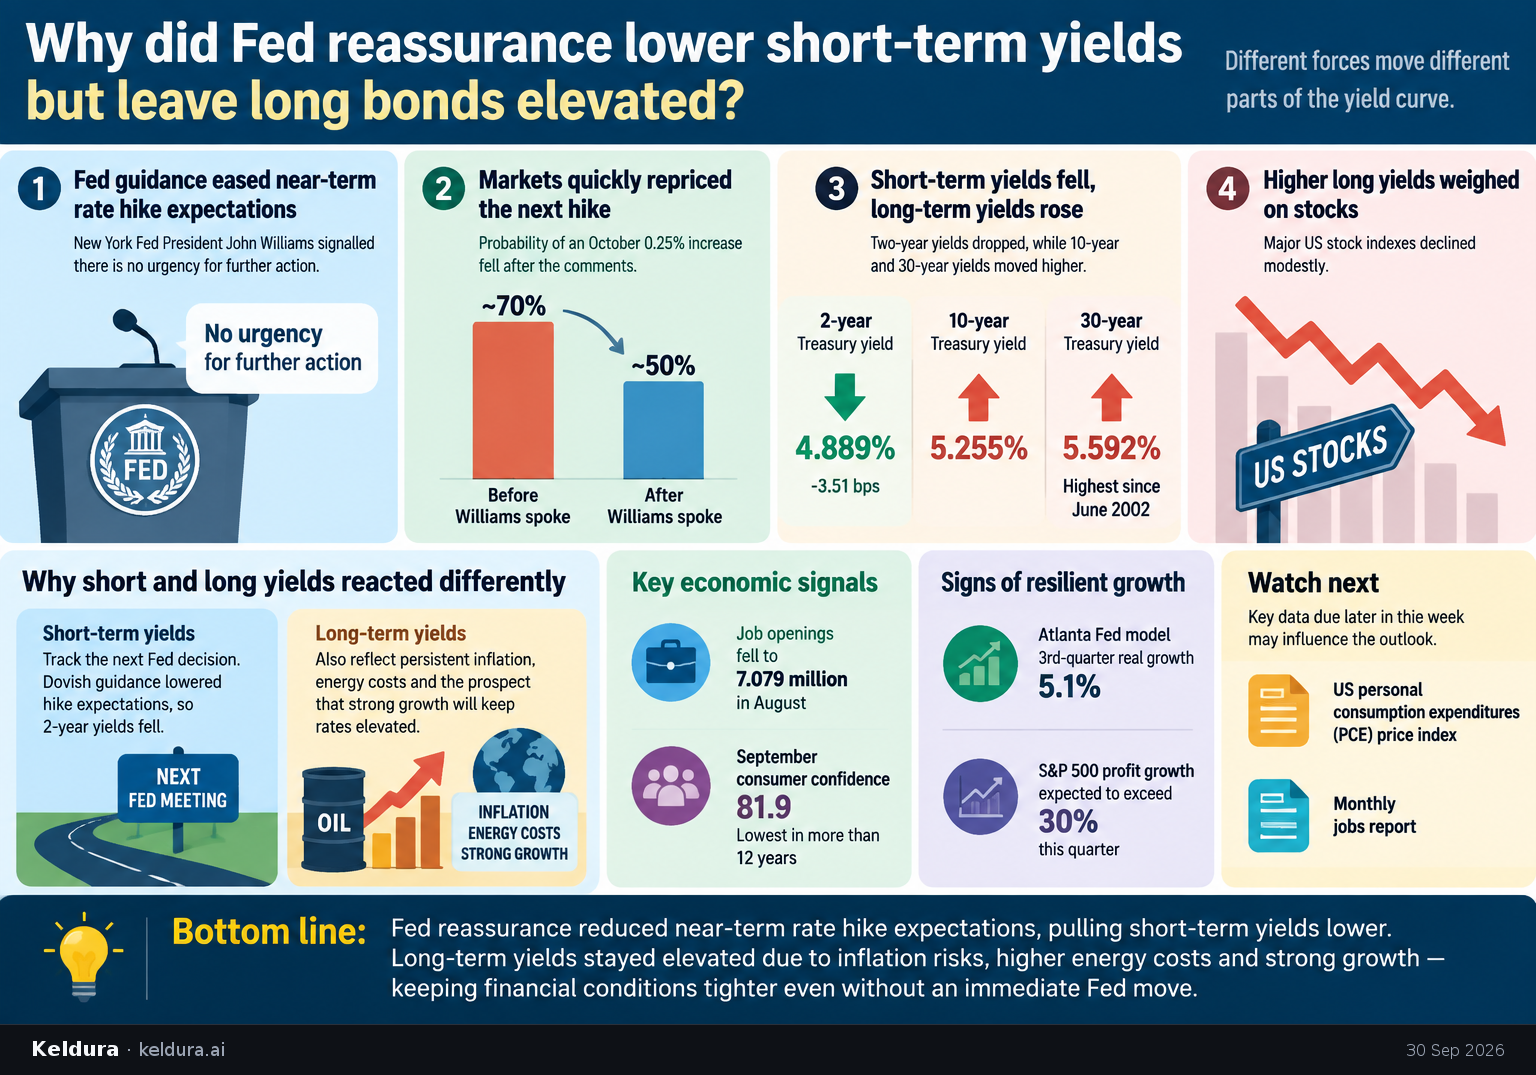
The two-year Treasury yield fell to 4.889% after New York Fed President John Williams said there was “no urgency” for further action, reducing the market-implied probability of an October quarter-point increase from nearly 70% to about 50%.[1] The 10-year yield nevertheless rose to 5.255%, the 30-year yield reached its highest level since June 2002, and major US stock indexes declined modestly.[1]
Why it matters: The divergence reflects two different bets: short maturities track the next Fed decision, while longer maturities also absorb persistent inflation, energy costs and the prospect that strong growth will keep rates elevated.[1][7] Because Treasury yields help price mortgages, corporate debt and equities, sustained increases can tighten financial conditions even without another immediate Fed move.[1][7]
Key insights: The market’s October hike probability shifted from roughly 70% before Williams spoke to about 50% afterward, illustrating how policy guidance can rapidly reprice short-term debt.[1][2] | Job openings fell to 7.079 million in August and September consumer confidence registered 81.9, while the broader confidence reading was described as its lowest in more than 12 years.[1][2] | Long yields remained under pressure as oil-linked inflation concerns persisted; the 10-year Treasury briefly reached 5.2932%, its highest level since mid-June 2007.[1] | Strong growth and earnings may be cushioning the economy from higher yields: the Atlanta Fed model was tracking third-quarter real growth at 5.1%, while S&P 500 profit growth was expected to exceed 30% in the quarter.[7]
Cheatsheet facts: What changed: The two-year yield fell 3.51 basis points to 4.889%, while the 10-year rose to 5.255% and the 30-year climbed to 5.592%.[1] | Why now: Williams signalled no urgency after September’s rate increase, but investors still faced elevated inflation concerns, higher oil prices and strong economic growth.[1][7] | Watch next: The next observable tests are the US personal consumption expenditures price index and the monthly jobs report due later in the week.[1]
The two-year Treasury yield fell to 4.889% after New York Fed President John Williams said there was “no urgency” for further action, reducing the market-implied probability of an October quarter-point increase from nearly 70% to about 50%.[1] The 10-year yield nevertheless rose to 5.255%, the 30-year yield reached its highest level since June 2002, and major US stock indexes declined modestly.[1]
Why it matters: The divergence reflects two different bets: short maturities track the next Fed decision, while longer maturities also absorb persistent inflation, energy costs and the prospect that strong growth will keep rates elevated.[1][7] Because Treasury yields help price mortgages, corporate debt and equities, sustained increases can tighten financial conditions even without another immediate Fed move.[1][7]
Key insights: The market’s October hike probability shifted from roughly 70% before Williams spoke to about 50% afterward, illustrating how policy guidance can rapidly reprice short-term debt.[1][2] | Job openings fell to 7.079 million in August and September consumer confidence registered 81.9, while the broader confidence reading was described as its lowest in more than 12 years.[1][2] | Long yields remained under pressure as oil-linked inflation concerns persisted; the 10-year Treasury briefly reached 5.2932%, its highest level since mid-June 2007.[1] | Strong growth and earnings may be cushioning the economy from higher yields: the Atlanta Fed model was tracking third-quarter real growth at 5.1%, while S&P 500 profit growth was expected to exceed 30% in the quarter.[7]
Cheatsheet facts: What changed: The two-year yield fell 3.51 basis points to 4.889%, while the 10-year rose to 5.255% and the 30-year climbed to 5.592%.[1] | Why now: Williams signalled no urgency after September’s rate increase, but investors still faced elevated inflation concerns, higher oil prices and strong economic growth.[1][7] | Watch next: The next observable tests are the US personal consumption expenditures price index and the monthly jobs report due later in the week.[1]
X copy pack
[1] GLOBAL MARKETS-Stocks dip, 2-year US yield falls after Fed's Williams cools rate hike bets | International — devdiscourse.com[7] ’G force’ driving world markets may need Fed and bond brake - The Globe and Mail — theglobeandmail.com[2] US STOCKS-S&P 500 flat as higher bond yields counter tech optimism | International — devdiscourse.comRead in BriefingsPost to X